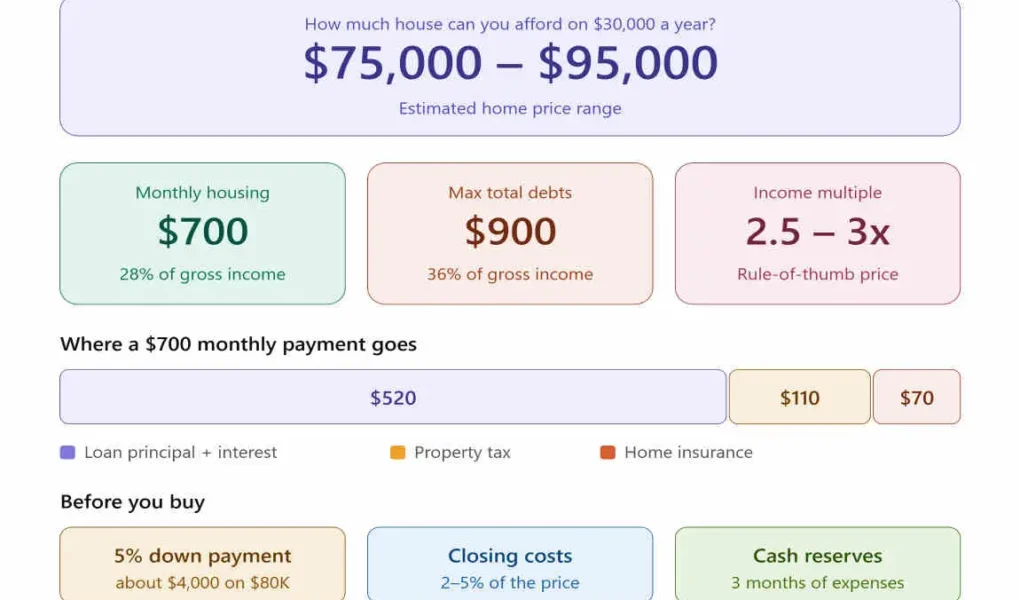
If you’ve ever typed “I make $30,000 a year, how much house can I afford?” into Google at 11 p.m., you’re in good company. It’s one of the most honest money questions out there, and the answer in late 2026 is a mix of good news, bad news, and a few clever workarounds.
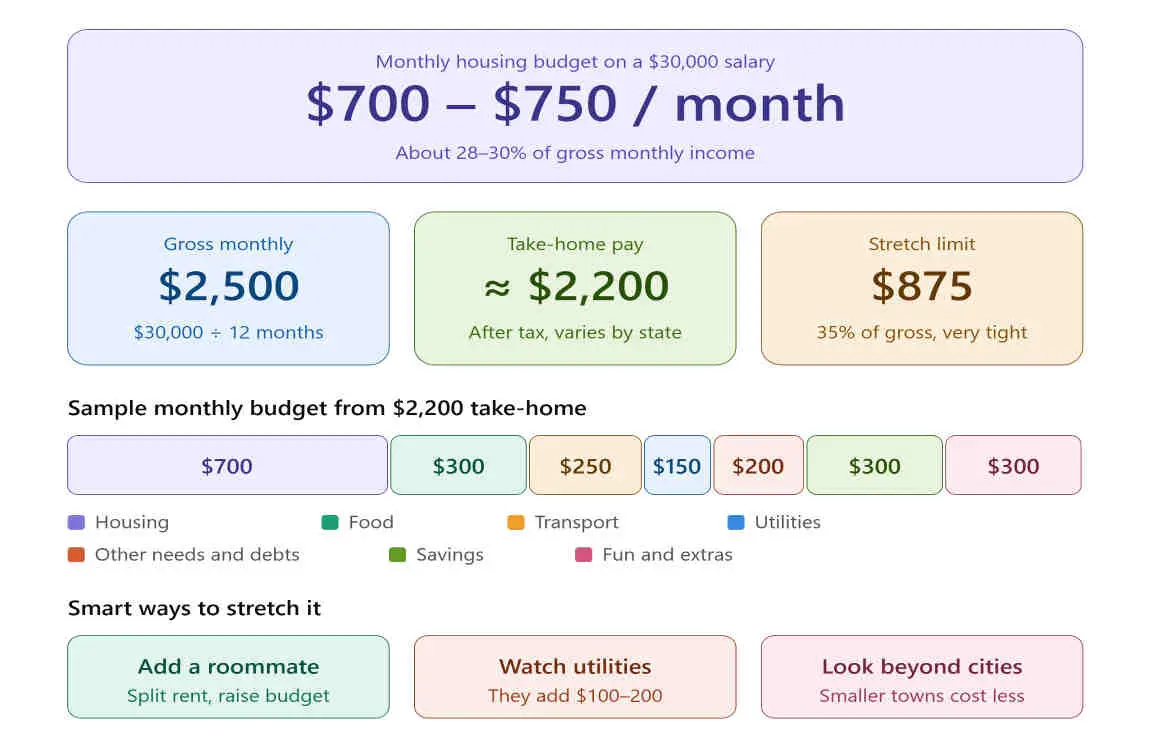
Start With the Reality Check: Where Prices Stand Right Now
Let’s not sugarcoat it. The National Association of Realtors reported that the median existing-home price hit $417,500 in September 2026, up 1.3% from a year earlier and the 39th straight month of annual gains (NAR). That’s roughly 14 times a $30,000 salary.
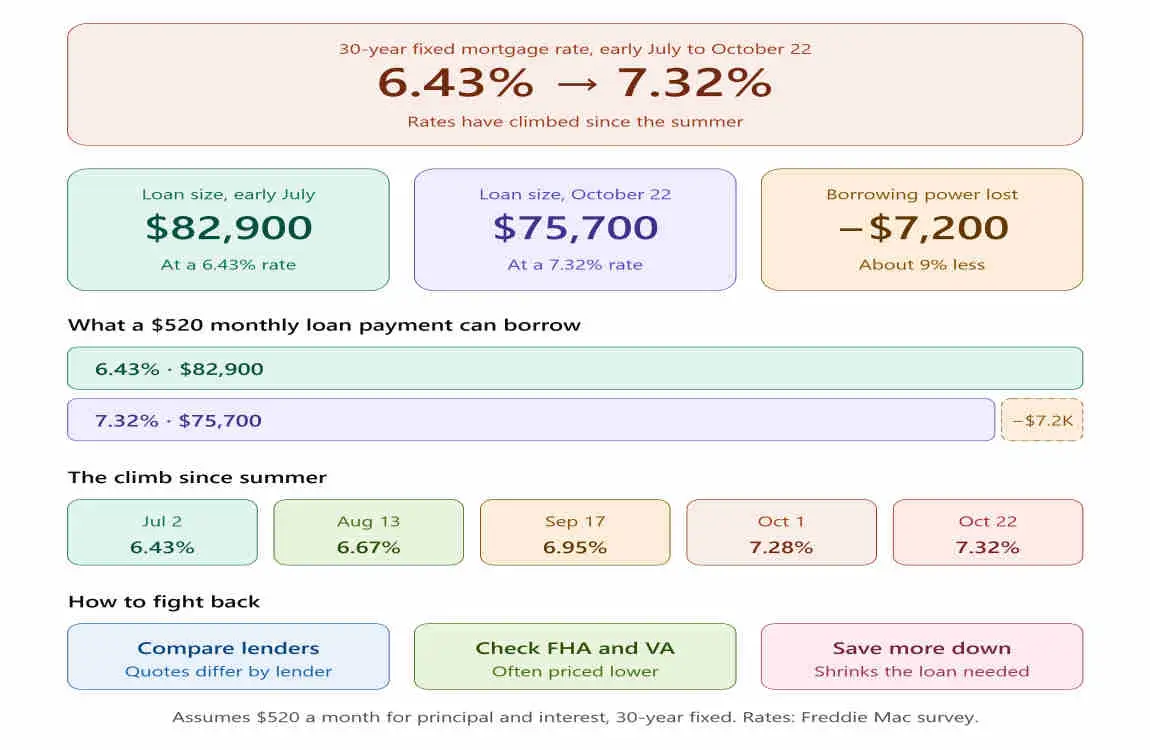
Borrowing is also pricey. Freddie Mac’s weekly survey put the average 30-year fixed rate at 7.32% on October 22, 2026, down from 7.40% the week before but well above the 6.19% of a year ago (Freddie Mac). Rates climbed through September and crossed 7% for the first time since January 2025.
How Lenders Decide What You Can Afford
Lenders don’t just look at your salary. They look at two ratios.
The front-end ratio (your housing costs)
This is your total monthly housing payment, which includes principal, interest, property taxes, homeowners insurance and mortgage insurance, divided by your gross monthly income. A common guideline is 28%. FHA loans allow a bit more, with standard limits of about 31% for housing.
The back-end ratio (all your debts)
This adds your car loan, student loans, credit card minimums and other monthly debts to the housing payment. The Consumer Financial Protection Bureau explains that 43% has long been a key debt-to-income benchmark. On $2,500 a month, 43% is $1,075 for all debts combined. If you already pay $400 toward a car and a credit card, that leaves only about $675 for housing.
The Numbers: What $30,000 a Year Actually Buys
Here’s a realistic estimate using a 30-year fixed FHA-style loan with 3.5% down, an interest rate near 7.23% (roughly where FHA rates have been sitting), property taxes around 1.1% of the home price, $1,500 a year in homeowners insurance, and annual FHA mortgage insurance of 0.55%. Rounded, and assuming no other monthly debts:
| Budget approach | Monthly housing budget | Estimated max price at ~7.23% | Estimated max price if rates fall to 6.5% |
|---|---|---|---|
| Cautious (25% of income) | $625 | about $63,000 | about $67,000 |
| Standard (28% of income) | $700 | about $72,500 | about $77,000 |
| Stretch (31% FHA limit) | $775 | about $82,000 | about $87,000 |
These are estimates for illustration. Taxes, insurance and mortgage insurance vary a lot by state and property. Ask a lender for a Loan Estimate for exact figures.
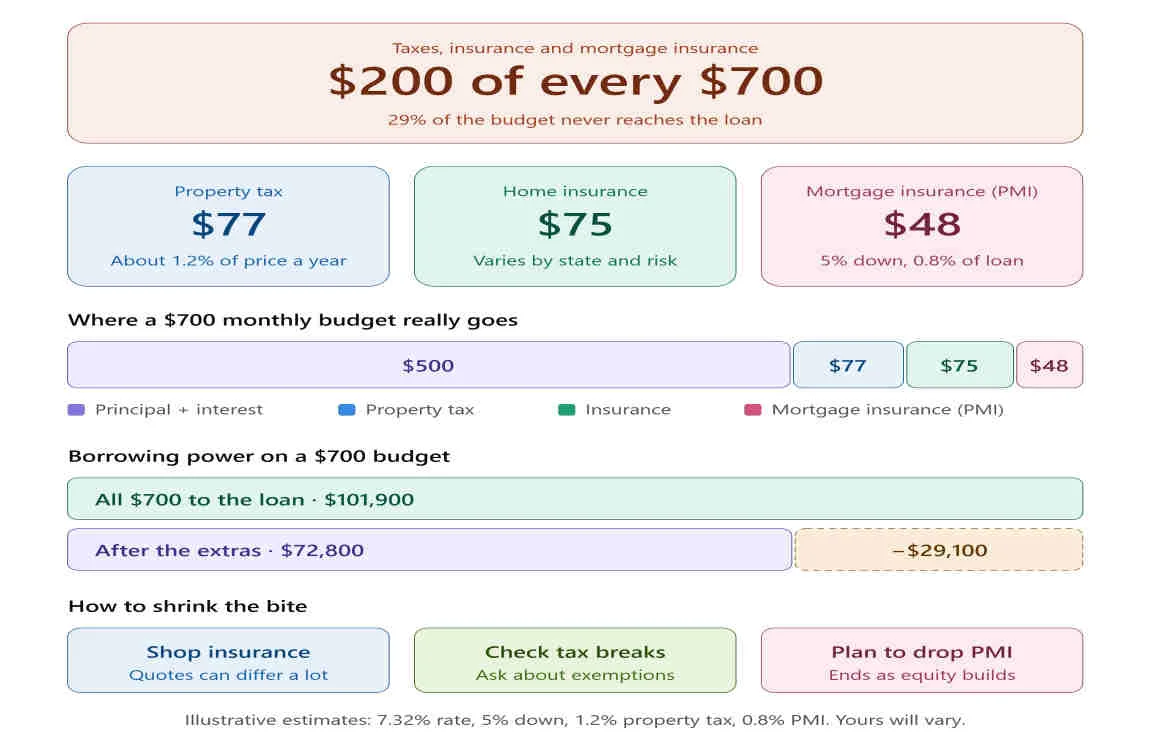
What a $700 Monthly Payment Is Made Of
Many first-time buyers focus on the loan payment and forget the rest. On a roughly $72,500 home, the full monthly payment looks like this:
The Hidden Costs Nobody Puts in the Listing
- Closing costs. Expect a few percent of the price on top of your down payment. The CFPB’s Owning a Home tools walk you through the Loan Estimate and Closing Disclosure.
- Maintenance. Budget around 1% of the home’s value per year for repairs, more for older homes.
- Utilities and HOA fees. These are not part of your mortgage payment but they are part of the cost of living there.
- An emergency fund. A broken water heater should be an annoyance, not a crisis.
Loan Programs That Make a $30,000 Income Work Harder
The right loan can matter more than the salary. Here are the programs worth a look.
FHA loans
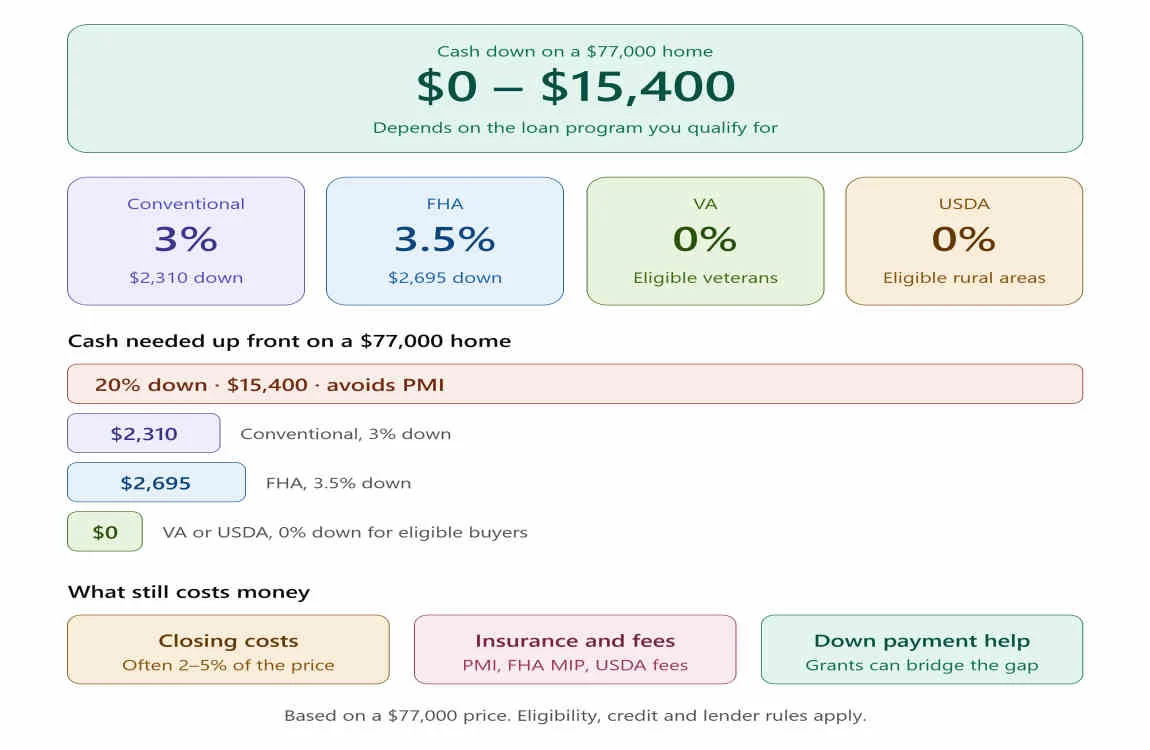
The Federal Housing Administration insures loans that allow low down payments. According to HUD-backed guidelines, borrowers with a credit score of 580 or higher can put down as little as 3.5%, while scores from 500 to 579 generally require 10% down. FHA also doesn’t set a minimum income, though lenders must verify steady earnings. Start at HUD’s home loan page. Keep in mind many lenders set stricter credit minimums than FHA itself.
USDA loans (no down payment)
If you’re looking in a qualifying rural or small-town area, a USDA guaranteed loan can allow zero down payment, with income limits based on your area. Check eligibility on the USDA Rural Development site.
VA loans (no down payment)
Veterans, active-duty service members and eligible spouses can often buy with no down payment through the VA home loan program.
Low down payment conventional loans
Programs like Fannie Mae’s HomeReady are built for low- to moderate-income buyers and can allow as little as 3% down. Your credit score decides whether these beat FHA.
7 Smart Ways to Stretch a $30,000 Income
- Pay down debt first. Every $100 in monthly debt payments cuts your housing budget by roughly $100.
- Add a co-borrower. A partner, spouse or family member with income can double your buying power. Their debts count too.
- Search lower-cost markets. Small towns, older condos and manufactured homes on owned land can sit far below the national median.
- Look for down payment assistance. State housing finance agencies and local nonprofits often offer grants or second loans for first-time buyers. Ask any HUD-approved housing counselor.
- Raise your credit score. A better score can lower your rate, and a lower rate directly raises the price you can afford.
- Consider a house hack. Buying a duplex and renting one side can help you qualify, since lenders may count some projected rental income.
- Shop at least three lenders. Rates and fees differ, and the CFPB encourages comparing Loan Estimates side by side.
Should You Buy a House on $30,000 a Year?
It’s possible, but it’s not automatically wise. Ask yourself:
- Is my income stable, or could it drop?
- Can I still cover the payment if taxes or insurance rise?
- Will I stay in the home at least five years?
- Do I have savings left after the down payment and closing costs?
If you answered yes to most of these, you’re in a stronger position than the headline numbers suggest. If not, spending another six to twelve months building savings and improving your credit can make a bigger difference than any loan program.
Frequently Asked Questions
How much house can I afford if I make $30,000 a year?
With no other debt and a 30-year FHA-style loan near 7.2%, expect roughly $63,000 to $82,000. A co-borrower, assistance programs or lower rates can raise that figure.
Can I buy a house on $30,000 a year?
Yes, especially in lower-cost areas. With the national median existing-home price at $417,500, buyers at this income usually target affordable regions, smaller properties or use extra help like a co-borrower.
What credit score do I need?
FHA allows scores down to 580 with 3.5% down, or 500 to 579 with 10% down. Lenders often require more, commonly 600 to 620.
Is there a minimum income to qualify for a mortgage?
FHA doesn’t set a minimum income, but lenders must confirm stable, verifiable income and an acceptable debt-to-income ratio.
Will mortgage rates come down soon?
Nobody knows for sure. Rates eased slightly in late October after hitting a 2026 high, but forecasts differ. Don’t wait for a perfect rate. You can often refinance later if rates drop.
Final Thoughts
A $30,000 salary won’t buy the national median home in 2026, but it can still open the door to homeownership if you choose the right market, keep debt low and use the programs designed for buyers like you. Run your own numbers with a lender, talk to a HUD-approved housing counselor, and be honest about your budget. The best house is the one you can keep.