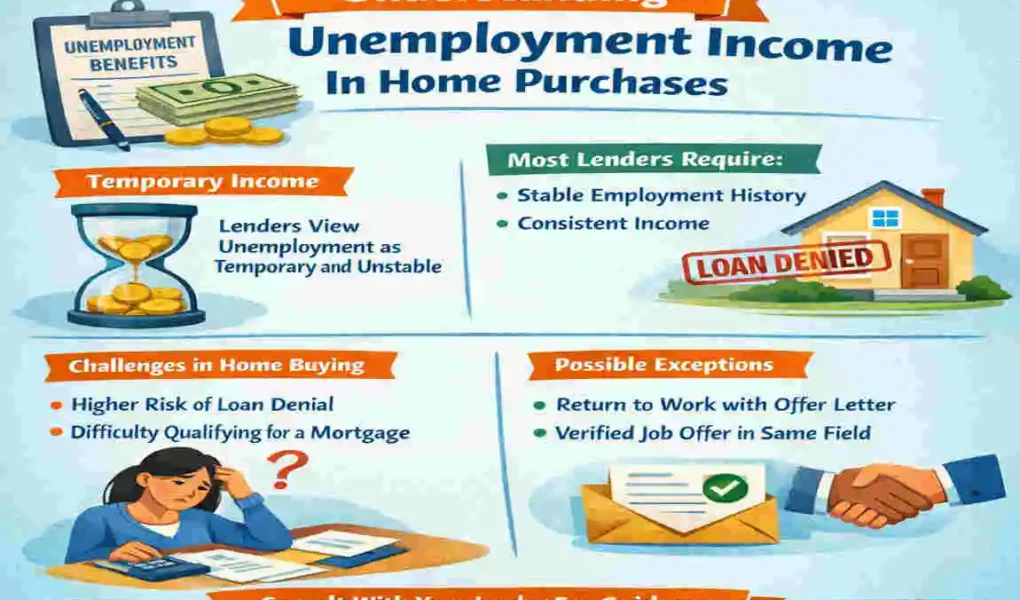
Buying a home usually comes down to one question: can you prove you can repay the loan? That is why income matters so much in mortgage approval.
| Topic | Key Information |
|---|---|
| Unemployment Income | Temporary benefits received after losing a job |
| Mortgage Eligibility | Depends on lender requirements and qualifying income |
| Income Verification | Benefit letters, bank statements, and financial records |
| Credit Score | Helps lenders assess borrowing risk |
| Debt-to-Income Ratio | Compares monthly debt payments with qualifying income |
| Savings | Can help cover down payment and closing costs |
| Co-Borrower Income | May help if the co-borrower meets lender requirements |
| Mortgage Options | Conventional, FHA, VA, or USDA loans, subject to eligibility |
| Main Challenge | Unemployment benefits may be temporary and may not qualify as mortgage income |
| Best Next Step | Contact a mortgage lender to review your financial situation |
If you are between jobs, it is natural to wonder whether unemployment counts as income when buying a house.
Understanding Whether Unemployment Benefits Count as Income
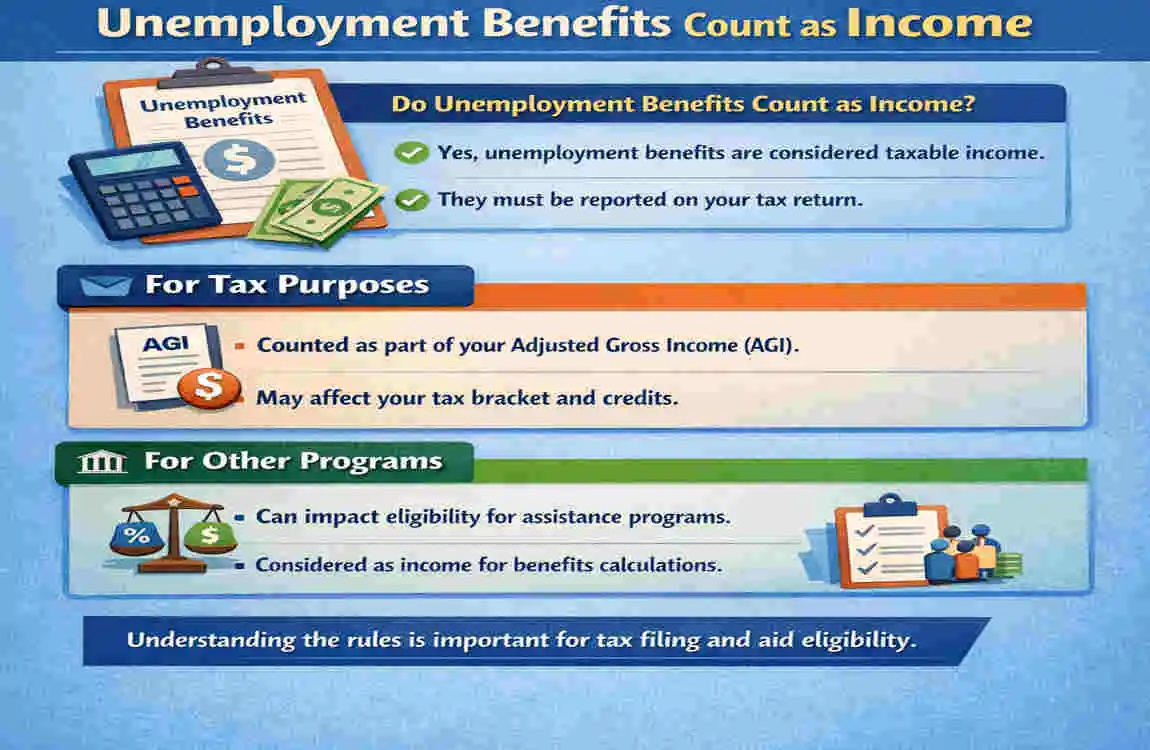
What unemployment benefits are
Unemployment benefits are payments that replace part of your lost wages after you lose your job. They are meant to support you while you look for work.
These benefits can help with everyday costs, but lenders often treat them differently from regular wages. Regular employment income is usually more dependable, while unemployment benefits are temporary.
Why lenders look at it differently
Mortgage lenders care about how long income will last and whether it will continue. If your only income is unemployment assistance, a lender may worry about your ability to keep up with monthly mortgage payments.
That does not mean unemployment benefits are useless. It means lenders usually review them cautiously and compare them with your other financial strengths.
How Mortgage Lenders Evaluate Unemployed Homebuyers
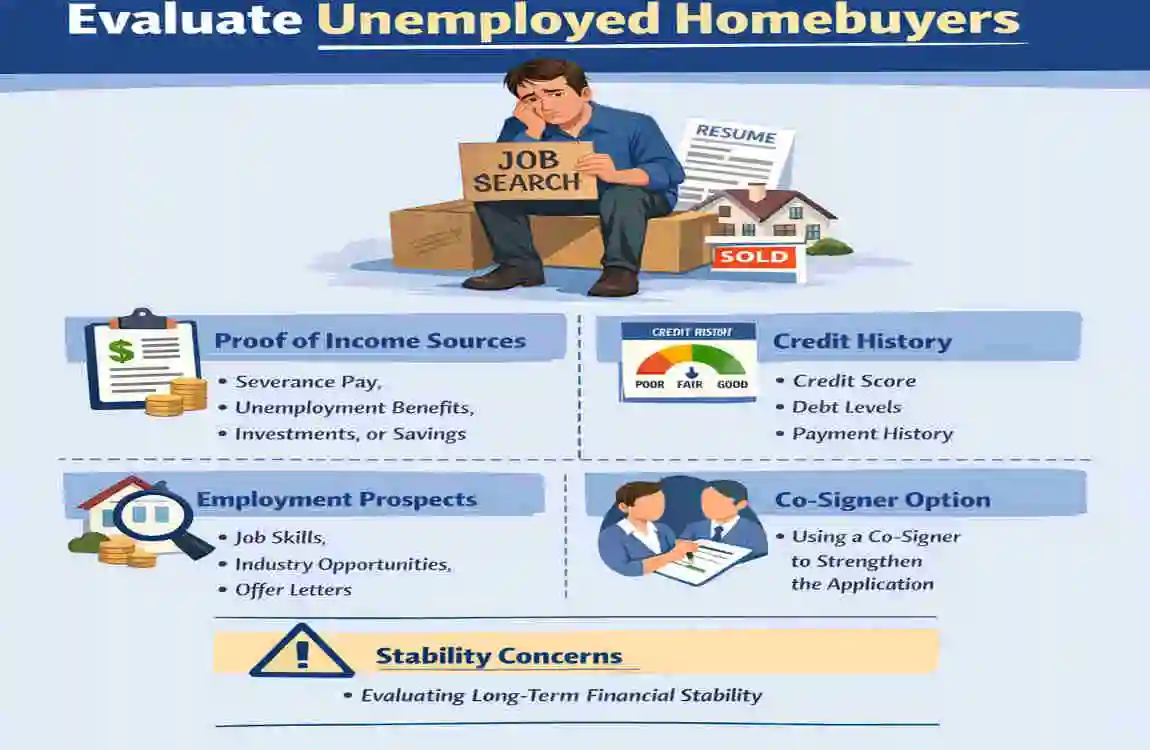
What lenders want to see
When you apply for a mortgage, the lender checks several things:
- Income and income history
- Credit score
- Monthly debt payments
- Debt-to-income ratio
- Savings and assets
- Employment history
If you are unemployed, the lender may ask for extra documents such as benefit award letters, bank statements, tax returns, or proof of other income. They want the full picture, not just one income source.
Why approval is not automatic
Receiving unemployment benefits does not guarantee approval. At the same time, it doesn’t always prevent approval.
If you have enough savings, another qualifying income source, or a co-borrower with high income, you may still have a path forward. The key is showing the lender that the loan is manageable.
Mortgage Options and Alternative Income Sources for Unemployed Buyers
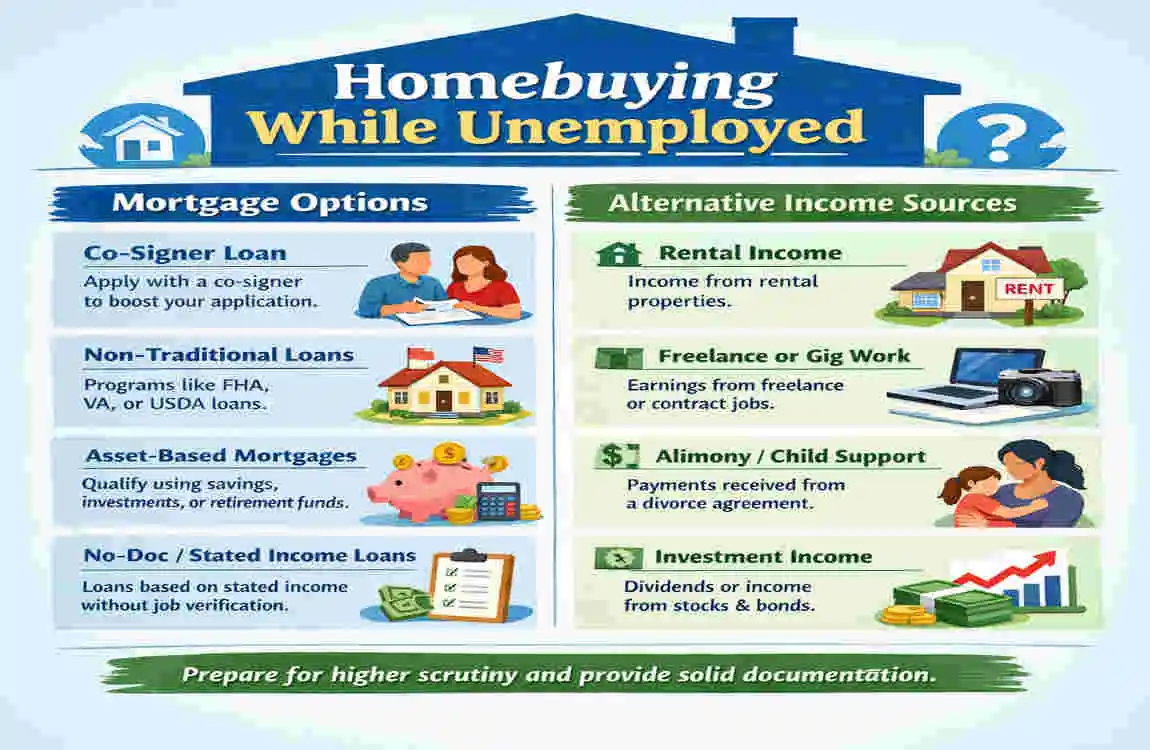
Loan types and income rules
Different loan programs have different rules. A conventional loan, FHA loan, VA loan, or USDA loan may each look at income a little differently.
Some lenders may be more flexible than others, but all still want proof you can repay what you borrow.
Other income that may help
If you do not have a job right now, other income sources may help strengthen your application, such as:
- Pension payments
- Social Security benefits
- Rental income
- Investment income
- Self-employment earnings
- A working spouse or co-borrower
Helpful financial strengths
A larger down payment can reduce how much you need to borrow. Strong savings can also give a lender more confidence.
Still, savings alone usually do not replace the need to show repayment ability. Lenders want to know you can handle the monthly payment after closing.
Quick Comparison of Income Sources
Income Source May Help With Mortgage? Why It Matters
Unemployment benefits Sometimes Temporary and may not be viewed as stable
Salary from a job Yes Usually the highest and most predictable income
Pension or Social Security Often Can be reliable if documented properly
Rental income Sometimes May count if it is consistent and verified
Savings Helps support the case Good for down payment and reserves, but not always qualifying income
Steps to Improve Your Chances of Buying a House While Unemployed
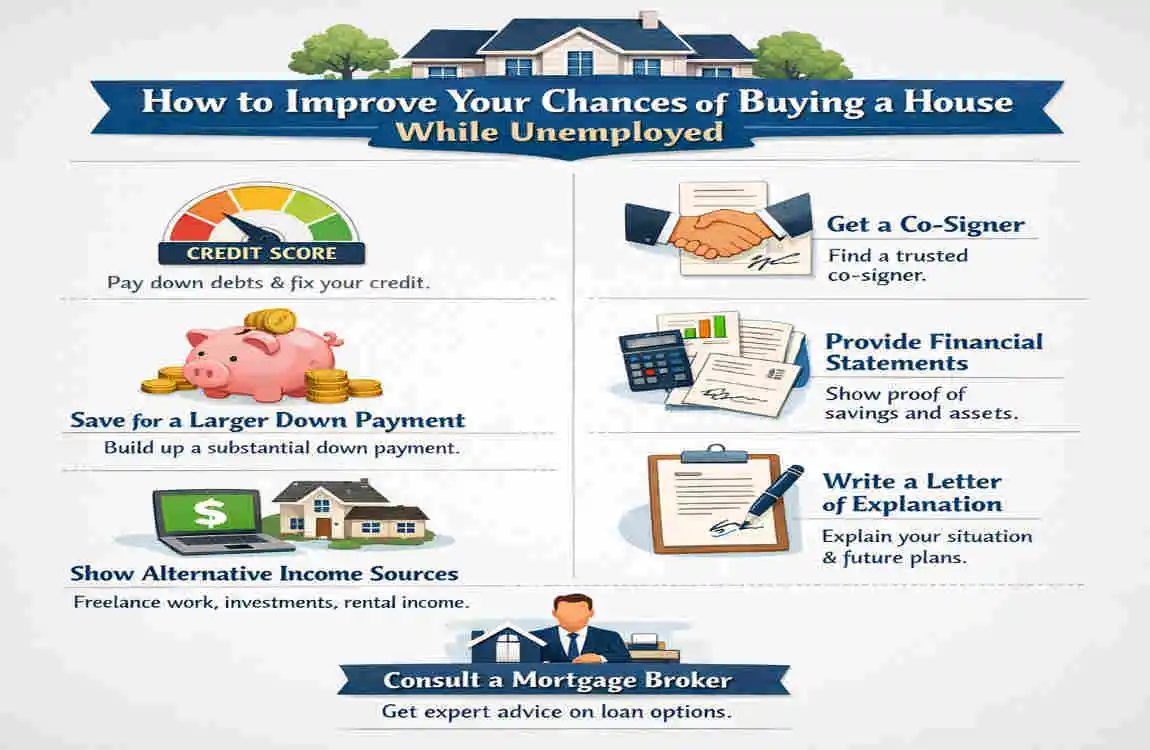
Get your finances ready.
Before you apply, review your credit report and fix any mistakes. Even a small error can hurt your chances.
Next, look at your monthly spending. Make sure you understand how much room you have for a mortgage payment, insurance, taxes, and home repairs.
Gather the right documents.
Organise your paperwork early. You may need:
- Unemployment benefit records
- Recent bank statements
- Tax returns
- Proof of other income
- Debt statements
Speak with lenders before applying.
Not all lenders treat unemployment income the same way. That is why it is smart to ask questions before you submit an application.
You can also talk with a housing counsellor or mortgage professional. A quick conversation may save you time, stress, and unnecessary loan rejections.
Be careful with new debt.
Try not to open new credit cards, finance a car, or make other major financial changes while you apply. Lenders prefer stable finances during the process.
If your income is temporary and the numbers feel tight, waiting until you find work may be the safer choice.
Frequently Asked Questions (FAQ)
Does unemployment count as income when buying a house?
It may be considered in some cases, but lenders usually want income that is documented, eligible, and dependable. Temporary unemployment benefits may not be enough on their own for a mortgage.
Can I get a mortgage if I am unemployed?
Yes, possibly. You may still qualify if you have other acceptable income, a strong co-borrower, savings, or a loan program that fits your situation.
Do FHA loans accept unemployment benefits as income?
FHA loans have their own rules, but unemployment benefits are not automatically accepted as qualifying income. The lender will still review whether the income is stable enough to repay the loan.
Can I buy a house using unemployment benefits and savings?
Savings can help with the down payment, closing costs, and emergency expenses. But the lender will still need to see how you will keep up with the mortgage each month.
Does a spouse’s income help me qualify for a mortgage while unemployed?
Yes, a spouse’s income can help if you apply together and their income, credit, and debts meet the lender’s requirements.
Should I wait until I find a job before buying a house?
In many cases, yes. If your benefits are temporary or your finances feel stretched, waiting for stable employment can reduce risk and make approval easier.